Private real estate funds give investors a way to own a share of a professionally managed real estate portfolio without buying, financing, or operating properties themselves.
They also work differently from most investments held in a brokerage account. Interests are purchased through private offering documents, values are reported periodically, eligibility rules usually apply, and capital is typically committed for years.
That combination rewards preparation. Investors who understand how a fund is structured, who is allowed to invest, and what to examine in the manager and the documents are better positioned to decide whether a particular fund belongs in their portfolio.
This guide covers how private real estate funds work, the main fund types and strategies, how they compare with REITs, who can invest, and what to evaluate before committing capital.
A private real estate fund is a pooled investment vehicle. Capital from multiple investors is combined and invested by a fund manager according to a strategy described in the fund’s offering documents.
The word “private” describes how the fund raises money. These funds are generally offered through private placements that are exempt from SEC registration, and the funds themselves are typically unregistered. As a result, they are outside the regular public disclosure requirements that apply to registered investments.1
Depending on the strategy, a fund may own apartment communities, single-family rentals, industrial buildings, retail centers, land, development projects, or loans secured by real estate. Some funds spread capital across several property types and regions. Others concentrate on one property type or one market where the manager has deep local relationships and expertise.
In each case, the investor owns an interest in the fund, and the fund owns the underlying investments.
That structure separates a fund from a single-property syndication, where investors typically evaluate the exact asset before committing. For a closer comparison, see our guide to real estate syndication vs. a fund.
Most private real estate funds follow a similar framework, even though the specific terms vary from one offering to the next.
A typical fund is organized as a limited partnership or a limited liability company.
The relationship is governed by the offering documents, which commonly include a private placement memorandum (PPM), the partnership or operating agreement, and a subscription agreement. Those documents set out the strategy, fees and expenses, distribution terms, investor rights, and the manager’s obligations for the life of the investment.1
A fund’s life usually moves through four stages:
The most important structural difference among private real estate funds is how investors enter and exit.
A closed-end fund raises capital during a defined offering period, invests it, and winds down over a set term that often spans several years or longer. Investors generally receive their capital back as properties are sold, and early withdrawals are usually limited or unavailable.
An open-end, or evergreen, fund has no fixed end date. It may accept new capital on an ongoing basis and offer periodic redemption windows. Those redemptions are typically subject to limits, notice periods, and manager approval, and they can be reduced or suspended when requests exceed available liquidity.
Some funds also use capital calls. Investors commit a total amount up front, and the manager draws that capital over time as investments are identified. Committed capital needs to remain available until it is called.
| Feature | Closed-end fund | Evergreen fund |
|---|---|---|
| Term | Defined life, often with extension options | No fixed end date |
| New investors | Accepted during the offering period | Often accepted on an ongoing basis |
| Accessing capital | Mainly through property sales near the end of the term | Periodic redemptions, subject to limits and approval |
| Capital deployment | Often called over time | Often invested at or soon after subscription |
| Valuation | Periodic, often appraisal-based | Periodic net asset value, often appraisal-based |
Fund cash flow generally comes from two sources: operating income, such as rent or loan interest, and proceeds from sales or refinancing.
The fund’s distribution waterfall determines how that cash is divided between investors and the manager. Many waterfalls return investors’ capital and pay a stated preferred return before the manager shares in profits through a carried interest or promote. Terms differ widely from fund to fund, so the waterfall deserves a careful read.
Distributions depend on the performance of the underlying investments and on the fund’s terms, and they are never guaranteed.
Managers often describe their strategy on a spectrum that runs from income-focused investments to higher-risk value creation.
| Strategy | What it generally targets | Typical risk profile |
|---|---|---|
| Core | Stabilized, well-leased properties held mainly for income | Lower |
| Core-plus | Generally stable properties with modest improvement potential | Lower to moderate |
| Value-add | Properties that need renovation, re-leasing, or repositioning | Moderate to higher |
| Opportunistic | Ground-up development, major redevelopment, or distressed assets | Higher |
| Debt | Loans secured by real estate, with income from interest | Varies with loan position and leverage |
Many funds blend more than one strategy, so the mix and how each piece is managed matter more than the label.
These labels are useful shorthand, and the industry applies them loosely. Two funds with the same label can carry very different levels of leverage, development exposure, and concentration.
Funds also differ in breadth. A diversified fund may spread capital across regions and property types. A focused fund may concentrate on one property type or one market, trading breadth for depth of local knowledge, relationships, and execution. Each approach carries its own risks, so the useful question is whether the strategy, the manager’s expertise, and the fund’s risk controls fit together.
Most private real estate funds raise capital under Regulation D, and the exemption a fund relies on shapes who is eligible to invest.
Most private funds are open to accredited investors. For individuals, the most common qualification paths are:2
Entities can qualify as well, for example when they own more than $5 million in assets or investments, or when all of their equity owners are accredited investors.2
Our guide to accredited investor rules for private real estate explains each test and the verification process in more detail.
Under Rule 506(b), a fund cannot use general solicitation. It may sell to an unlimited number of accredited investors and to a limited number of non-accredited investors who meet a sophistication standard, subject to additional disclosure requirements.3
Under Rule 506(c), a fund can advertise publicly. In exchange, every investor must be accredited, and the fund must take reasonable steps to verify each investor’s status.4
Some larger funds limit participation further, to qualified purchasers. Under the Investment Company Act, an individual generally qualifies as a qualified purchaser by owning at least $5 million in investments.5 Funds that rely on this standard are usually designed for institutions and very high-net-worth investors.
Each fund sets its own minimum investment, which is disclosed in the offering documents. Minimums for private real estate funds are often substantial, and some managers set different minimums for individuals and entities.
Real estate investment trusts offer another way to own professionally managed real estate. The comparison depends on which type of REIT is involved.6
| Feature | Publicly traded REIT | Non-traded REIT | Private real estate fund |
|---|---|---|---|
| How it is offered | Registered with the SEC and listed on a stock exchange | Registered with the SEC, sold without an exchange listing | Private placement, generally exempt from SEC registration |
| How shares are bought | Through a brokerage account | Through a broker participating in the offering | Through the fund’s subscription documents |
| Liquidity | Shares trade daily | Limited, often through redemption programs | Limited, set by the fund’s terms |
| Pricing | Market price, updated continuously | Periodic estimated value | Periodic, often appraisal-based |
| Who can invest | Generally any investor | Investors who meet the offering’s standards | Generally accredited investors |
Private funds and REITs can each play a role in a portfolio. Public REITs offer daily liquidity and market pricing. Private funds offer direct, strategy-specific exposure with less frequent valuation and longer holding periods.
Valuation deserves particular attention with any non-traded vehicle. Investor.gov cautions that the value of a non-traded REIT share can be difficult to determine for a significant period after investing.6 Private funds raise the same question, which makes a manager’s valuation policy and reporting quality worth close review.
Investors consider private real estate funds for several reasons:
Whether any of these benefits applies depends on the specific fund, its terms, and the investor’s own situation.
Every private real estate fund carries risk, and several of the most important risks come from the structure itself.
The risk factors in a fund’s PPM describe the specific risks of that offering in detail and should be read in full.
Evaluating a private fund means reviewing three things together: the manager, the strategy, and the terms.
Investor.gov encourages investors to be vigilant about the fees and expenses tied to a private fund investment and alert to conflicts of interest between a manager and the funds it manages.1
A few public resources help investors confirm basic facts:
A private real estate fund is a pooled investment vehicle that combines capital from multiple investors and invests it in real estate according to a defined strategy. It is offered privately, usually to accredited investors, and managed by a sponsor or general partner.
Funds can earn operating income, such as rent or loan interest, and gains when properties are sold or refinanced. The fund’s distribution waterfall sets how that cash is shared between investors and the manager. Returns are never guaranteed.
Most private real estate funds are limited to accredited investors. Some Rule 506(b) offerings allow a limited number of sophisticated non-accredited investors, and some larger funds are limited to qualified purchasers. Each fund’s offering documents state its eligibility requirements.
Generally, no. Closed-end funds usually return capital as properties are sold near the end of the fund’s term. Evergreen funds may offer periodic redemptions, which are typically limited and can be reduced or suspended.
Publicly traded REITs are registered with the SEC and trade on stock exchanges, so their shares can be bought and sold daily. Private real estate funds are offered through private placements, are generally limited to accredited investors, and offer limited liquidity under the fund’s terms.
A capital call is a request from the fund manager for investors to contribute part of their committed capital. Funds that use capital calls draw commitments over time as investments are identified, so investors need to keep committed funds available.
Funds organized as partnerships generally report each investor’s share of income, deductions, and credits on a Schedule K-1. IRAs that invest in funds using debt-financed property may owe tax on unrelated business income. Tax treatment depends on the fund’s structure and each investor’s situation, so review it with a tax adviser.
Each fund sets its own minimum, which is stated in its offering documents. Minimums for private real estate funds are often substantial and can differ for individuals and entities.
Private real estate funds combine professional management, access to larger investments, and diversification within real estate. In exchange, investors accept limited liquidity, eligibility requirements, and a high degree of reliance on the manager.
Investors who are well served by private funds tend to share a few habits. They read the offering documents closely, ask direct questions about fees, leverage, and valuation, confirm basic facts through public resources, and match the fund’s time horizon to their own.
Eligibility rules determine who may invest. The manager, the strategy, and the terms determine whether a particular fund deserves your capital.
This article is for educational purposes only. Novacrest offerings are available to verified accredited investors through official offering documents. Nothing in this article constitutes investment, legal, tax, or financial advice. Private real estate investments involve risk, including possible loss of principal. Prospective investors should review all offering documents and consult their own attorney, accountant, and financial adviser before investing.
Private real estate investing often introduces investors to a term they may not encounter in public markets: accredited investor.
For many private real estate funds, syndications, and other private offerings, accredited investor status determines whether an individual or entity is eligible to participate.
The definition comes from Rule 501(a) of Regulation D, and qualification can be based on income, net worth, certain professional credentials, or other specific criteria. For investors considering a Rule 506(c) offering, there is another step to understand: the sponsor must take reasonable steps to verify that each purchaser is actually accredited.1
That verification requirement can lead to questions.
Why does the sponsor need financial documentation? Does a primary residence count toward net worth? Can a CPA verify accreditation? What happens if an investor has qualified before?
This guide explains how the accredited investor rules apply to private real estate and what investors can expect during the Rule 506(c) verification process.
An accredited investor is a person or entity that meets one of the qualification standards established by the Securities and Exchange Commission.
The definition matters because many private securities offerings rely on exemptions from SEC registration under Regulation D. Those exemptions often limit who can participate or establish different requirements depending on whether an investor is accredited.2
Private real estate offerings frequently fall into this category.
An investment in a real estate syndication, private real estate fund, development project, or other pooled vehicle may involve the purchase of securities, even though the underlying asset is real property.
As a result, securities laws can affect both how the investment is marketed and who may invest.
For individual investors, there are several ways to qualify.
| Qualification method | General SEC standard |
|---|---|
| Net worth | More than $1 million individually or jointly with a spouse or spousal equivalent, excluding the value of the primary residence |
| Individual income | More than $200,000 in each of the prior two years, with a reasonable expectation of reaching the same level in the current year |
| Joint income | More than $300,000 with a spouse or spousal equivalent in each of the prior two years, with a reasonable expectation of reaching the same level in the current year |
| Professional credentials | Certain investment professionals holding qualifying licenses in good standing, currently including Series 7, Series 65, and Series 82 |
| Certain insiders | Directors, executive officers, or general partners of the company issuing the securities, or qualifying persons associated with its general partner |
| Certain private-fund employees | Certain “knowledgeable employees” may qualify for investments in the private fund with which they are associated |
The SEC also recognizes several categories of accredited entities, including certain financial institutions, investment advisers, entities meeting applicable asset or investment thresholds, and entities whose equity owners are all accredited investors.2
For most individual private real estate investors, the income and net-worth tests remain the most familiar qualification paths.
An individual may qualify as an accredited investor when their net worth, either alone or together with a spouse or spousal equivalent, exceeds $1 million.
The value of the investor's primary residence is generally excluded from the calculation.2
That distinction can be important.
Consider an investor with:
The home equity generally does not move the investor toward the $1 million accredited-investor threshold. That leaves $750,000 counting toward the test, so this investor would not meet the net-worth threshold on these assets alone.
The investor would need to evaluate the assets and liabilities that properly count under the SEC's rules to determine whether the net-worth requirement is met.
Investors approaching the threshold should work through the calculation with their attorney, CPA, financial adviser, or the verification professional handling the offering.
Income provides another path.
An individual generally qualifies if they earned more than $200,000 individually in each of the two most recent years and reasonably expect to reach the same income level during the current year.
For joint qualification with a spouse or spousal equivalent, the threshold is more than $300,000 in each of the prior two years, together with a reasonable expectation of reaching that level again during the current year.2
That means a single high-income year by itself does not ordinarily satisfy the test.
For example, an investor earning:
would generally fall short of the individual income test because the $200,000 threshold was not exceeded in both prior years.
Depending on the investor's circumstances, another qualification method such as net worth or a qualifying professional credential could still apply.
Certain investment professionals can also qualify through credentials that the SEC has designated as demonstrating sufficient financial sophistication.
The SEC currently recognizes individuals holding the following licenses in good standing:
Those credentials provide another route to accredited investor status even when the traditional income or net-worth thresholds are not met.2
Private real estate investments are often made through LLCs, trusts, retirement structures, partnerships, or other entities.
Those investors have separate qualification rules.
Depending on the type of entity, accredited status may be available when the entity has more than $5 million in assets or investments, meets another category specifically identified in Rule 501(a), or has equity owners who are themselves accredited investors.2
Trusts have additional requirements depending on how they qualify.
Because entity qualification can become more technical than the standard individual income and net-worth tests, investors using an LLC, trust, family office, retirement account, or similar structure should determine which provision of Rule 501(a) actually applies to the investing entity.
The fact that an individual owner is accredited does not automatically answer every question about an entity's eligibility.
Private real estate sponsors often raise capital through Regulation D, which provides exemptions from the traditional SEC registration process.
Two commonly discussed pathways are Rule 506(b) and Rule 506(c).
Both can be used to raise an unlimited amount of capital, but their treatment of marketing and investor eligibility differs substantially.
Rule 506(b) generally prohibits general solicitation and advertising.
The rule permits sales to an unlimited number of accredited investors and, subject to additional requirements, up to 35 non-accredited investors during the applicable period who satisfy the required sophistication standard.3
Because public solicitation is restricted, the relationship between the sponsor and prospective investors becomes important.
Rule 506(c) allows sponsors to broadly solicit and advertise an offering.
That could include marketing through publicly accessible websites or other forms of general solicitation.
In exchange for that flexibility, every purchaser must be accredited, and the issuer must take reasonable steps to verify accredited investor status.1
For investors, that verification requirement is the practical distinction they are most likely to notice.
The SEC's current guidance treats the two rules differently, and the difference explains why some investors are asked for more than a check-the-box investor questionnaire.
Under Rule 506(b), the issuer generally needs a reasonable belief that an investor meets the accredited investor standards.
Rule 506(c) imposes a separate requirement: the issuer must take reasonable steps to verify the investor's status.4
The SEC explicitly states that self-certification by itself (for example, checking a box without the issuer having additional information) is insufficient to meet the Rule 506(c) verification requirement.4
That is why an investor entering a 506(c) real estate offering may be asked for supporting documentation or a verification letter even when they have invested in private offerings before.
The SEC uses a principles-based standard.
The issuer has to evaluate whether its verification process is reasonable based on the circumstances of the investor and the transaction.
Factors can include the type of accredited investor involved, the information the issuer already possesses, the way the investor was solicited, and the terms of the offering.4
The rules also provide several non-exclusive verification methods.
An investor qualifying based on income may provide IRS documents reporting income.
Examples identified by the SEC include forms such as:
The documentation is used to substantiate income for the relevant prior years.4
For investors using the net-worth qualification, the verification process may involve reviewing recent documentation showing assets and liabilities.
The SEC identifies examples including bank statements, brokerage statements, certificates of deposit, tax assessments, and a consumer credit report.
Relevant documents generally must be dated within the prior three months under this verification method, and the investor must also provide the required written representation.4
Many investors prefer third-party verification because it can reduce the amount of sensitive financial information being sent directly to the real estate sponsor.
The SEC allows an issuer to rely on written confirmation from certain professionals, including a:
The professional must state that, within the prior three months, they took reasonable steps to verify the investor's accredited status and determined that the investor qualifies.4
For investors already working with a CPA, attorney, or adviser, this can be a relatively straightforward path.
Potentially, but the SEC's rules provide some flexibility for previously verified investors.
If an issuer previously took reasonable steps to verify that an investor was accredited, a written representation from that investor can satisfy the verification obligation for subsequent sales for up to five years from the prior verification, provided the issuer is not aware of information suggesting that the investor no longer qualifies.4
The exact process still depends on the issuer, offering, and verification approach being used.
Investors should therefore expect different sponsors or fund administrators to request different documentation.
An important development came from SEC staff guidance issued in March 2025.
SEC staff agreed that, under the particular circumstances described in a no-action request from Latham & Watkins, a sufficiently high minimum investment could be relevant to determining whether an issuer had taken reasonable steps to verify accreditation.
The approach described:
combined with written representations regarding accredited status and confirmation that the minimum investment was not financed by a third party specifically for the purpose of making that investment.5
The March 2025 letter represents the views of SEC staff based on the specific facts presented. The SEC notes that a no-action letter does not have the force of a Commission rule and that different circumstances can lead to a different conclusion.5
The SEC's accompanying interpretive guidance nevertheless confirms that a high minimum investment can be one factor in the broader facts-and-circumstances analysis of whether reasonable verification steps were taken.6
Investors should therefore follow the process established by the issuer and its securities counsel. A large investment by itself does not automatically eliminate verification requirements.
Receiving a request for tax documents, investment statements, or verification from a CPA can initially feel intrusive.
In a Rule 506(c) offering, the sponsor has a regulatory obligation to establish a reasonable verification process.
The requirement belongs to the issuer.
Verification is one of the conditions of Rule 506(c) itself, so the issuer has to complete it even when an investor clearly appears to qualify.1
Investors who prefer to limit the financial information provided directly to the sponsor can ask whether third-party verification is available.
In many offerings, that allows a qualified professional or verification provider to review the underlying documents and give the issuer confirmation of accredited status.
Accredited investor status establishes eligibility under particular securities rules, and it carries no SEC endorsement of an investor, an offering, or the sponsor managing it.
An investor can meet the accredited investor definition and still face substantial risk in a private real estate investment.
Private offerings may involve illiquidity, leverage, development risk, operational risk, market concentration, unfavorable financing conditions, and the possibility of losing some or all invested capital.
Accreditation should therefore be viewed as one component of the investment process.
The underlying opportunity still deserves independent due diligence.
For a private real estate investment, that generally means understanding the property or strategy, sponsor track record, financing, assumptions, fee structure, expected hold period, distribution provisions, conflicts of interest, and downside scenarios.
For an investor, the process often looks something like this:
The details vary by offering, but seeing a verification request in a Rule 506(c) investment is generally part of the expected compliance process.
An individual can generally qualify with a net worth of more than $1 million, either individually or jointly with a spouse or spousal equivalent. The value of the investor's primary residence is excluded under the SEC's calculation rules.
An individual generally qualifies with income exceeding $200,000 in each of the prior two years, together with a reasonable expectation of reaching the same level during the current year. Joint income with a spouse or spousal equivalent must generally exceed $300,000 during each of those prior two years, with the same expectation for the current year.
Generally, the value of an investor's primary residence is excluded when determining whether the investor meets the accredited investor net-worth threshold.
It depends on the offering. A Rule 506(c) offering can sell only to accredited investors. Rule 506(b) can permit a limited number of qualifying non-accredited investors, subject to additional requirements. Other securities exemptions may also have different investor eligibility rules.
Self-certification alone does not satisfy the Rule 506(c) reasonable-steps-to-verify requirement when the issuer has no additional information supporting the investor's status.
Yes. Rule 506(c) permits an issuer to rely on qualifying written confirmation from a CPA, licensed attorney, registered broker-dealer, or SEC-registered investment adviser when the applicable requirements are satisfied.
For an investor whom an issuer previously took reasonable steps to verify, the SEC provides a method allowing a written representation to support subsequent investments for up to five years from the original verification, provided the issuer has no information indicating that the investor no longer qualifies.
Accredited investor rules affect access to a significant portion of the private real estate market.
For most individual investors, qualification will come through income, net worth, or an eligible professional credential. Investors considering publicly marketed Rule 506(c) offerings should also expect their accredited status to be verified before the investment is accepted.
Understanding that process ahead of time can make the subscription process more straightforward and help investors distinguish regulatory eligibility from investment due diligence.
Before subscribing to a Rule 506(c) offering, investors can prepare by confirming which qualification method applies, keeping recent supporting documents on hand, and asking early whether a CPA, attorney, or adviser can provide a verification letter.
This article is for educational purposes only. Novacrest offerings are available to verified accredited investors through official offering documents. Nothing in this article constitutes investment, legal, tax, or financial advice. Private real estate investments involve risk, including possible loss of principal. Prospective investors should review all offering documents and consult their own attorney, accountant, and financial adviser before investing.
Investing in private real estate often begins with a seemingly simple question:
Do I invest in a specific deal, or do I invest in a fund?
Both can provide access to real estate without requiring you to personally find properties, manage tenants, oversee renovations, or negotiate financing.
But the similarities can stop there.
A real estate syndication generally raises capital around a particular property or investment opportunity. A real estate fund typically raises capital around a broader investment strategy, allowing the fund manager to deploy that capital across multiple properties or opportunities.
The difference changes what you know before investing, what you are relying on the sponsor to do, how diversified your capital may be, how fees are structured, and how long your money may remain invested.
For sophisticated investors, understanding those differences matters.
Before comparing projected returns, it helps to ask:
What am I actually investing in, who controls my capital, and what assumptions have to go right for this investment to perform?
A real estate syndication is an investment structure that allows multiple investors to pool their capital to acquire or participate in a real estate investment.
Instead of one investor purchasing an entire apartment community, industrial property, development, or other large asset, investors participate alongside a sponsor or General Partner.
The structure commonly involves two primary groups.
The sponsor typically identifies the opportunity and manages the investment.
Depending on the project, that can include:
Limited Partners, or LPs, generally provide most of the investment capital while remaining passive in the day-to-day operation of the property.
Their economic rights, voting rights, distributions, and responsibilities are defined by the offering and operating documents.
The important distinction is that investors in a typical syndication know the underlying opportunity before committing their capital.
For example, you may be evaluating a particular multifamily property in a particular market, with a specific purchase price, debt structure, renovation budget, business plan, sponsor, projected hold period, and exit strategy.
That specificity can be one of the biggest attractions of syndication investing.
A real estate fund also pools investor capital.
The difference is that rather than raising money around one identified property, a fund typically raises money around an investment mandate or strategy.
For example, a fund might be created to acquire:
Investors are therefore placing greater reliance on the fund manager's ability to identify opportunities after the capital has been committed.
Depending on the structure, investors may know some of the assets at the time they invest.
In other cases, few or none of the future acquisitions have been identified yet.
This is often referred to as a blind-pool structure.
That changes the underwriting question without making the investment inherently better or worse.
With a syndication, investors can heavily evaluate the individual property.
With a fund, the investor has to place significantly more weight on the manager, investment criteria, track record, risk controls, and capital allocation discipline.
At a high level, the comparison looks like this:
| Real Estate Syndication | Real Estate Fund | |
|---|---|---|
| Investment | Usually one identified asset or project | Usually multiple investments |
| Assets known upfront | Generally yes | Sometimes; often not all |
| Diversification | Concentrated | Potentially greater |
| Manager discretion | Primarily focused on executing one business plan | Greater discretion within the fund mandate |
| Investor diligence | Property + sponsor | Sponsor + strategy + portfolio construction |
| Capital deployment | Often invested at or near closing | May be called and deployed over time |
| Fees | Usually property/deal specific | May include ongoing fund-level management fees plus performance compensation |
| Liquidity | Generally limited | Generally limited; varies by fund structure |
| Tax reporting | Often tied to one investment/entity | Can become more complex across a portfolio |
| Exit | Often tied to sale/refinance of one asset | Determined by the fund structure and lifecycle |
There are exceptions to each of these, which is why investors should rely on the actual offering documents rather than the name attached to an investment vehicle.
This is arguably the most important difference.
Imagine you are considering a $100,000 investment into a real estate syndication.
Before investing, you may be able to review:
You can make a decision about both the operator and the opportunity.
Now consider investing that same $100,000 into a fund that plans to acquire ten properties over the next three years.
Some properties may not exist within the portfolio yet.
You therefore cannot underwrite them.
Instead, you have to ask:
Do I trust the manager's process for finding, underwriting, rejecting, acquiring, financing, managing, and exiting opportunities?
This makes fund-manager discipline critically important.
Sophisticated investors want to understand what a manager has purchased and what the manager is willing to walk away from.
Good investing includes the discipline to say no when the numbers do not make sense.
One misconception about syndications is that because investors know the property beforehand, they control the investment afterward.
Typically, they do not.
Limited Partners generally remain passive investors.
The sponsor or manager usually controls operational decisions such as:
Depending on the operating agreement, investors may have voting or approval rights around certain major events.
But those rights vary significantly.
A real estate fund can involve even more managerial discretion.
Investors are effectively telling the manager:
Here is the strategy I agreed to. Deploy my capital according to that strategy.
For that reason, the broader the manager's discretion, the more important manager selection becomes.
An investor should understand:
The word “passive” should never mean “uninformed.”
Funds often have a structural advantage when it comes to diversification.
A syndication might own one apartment complex.
If that property's market weakens, insurance costs rise materially, occupancy falls, financing becomes difficult, or the business plan fails, there may not be another asset inside the vehicle to offset the problem.
A fund holding ten or twenty investments may spread exposure across multiple properties.
Potentially across multiple:
But diversification should not automatically be confused with safety.
Twenty poorly underwritten investments do not necessarily create a strong portfolio.
Investors should understand what they are diversified across.
Ten properties purchased in highly correlated markets using similar floating-rate financing might look diversified by address while sharing many of the same underlying risks.
Diversification can come from strategy and exit options as well as geography. A portfolio focused on a single market can still spread risk by having more than one way to generate income and more than one path to exit.
This is where portfolio construction matters.
Fees are one of the most misunderstood parts of private real estate.
Real estate syndication fees vary by sponsor and deal, but investors may encounter items such as:
Not every transaction includes every fee.
Funds may use similar fees while also incorporating a fund-level management fee.
The specific structure matters more than whether a particular fee exists.
Investors should ask:
When does the manager earn money?
A manager compensated heavily simply for acquiring assets may have different incentives from one whose largest economic reward comes after investors have achieved agreed-upon return thresholds.
Either structure can be appropriate, and investors should understand the incentives each one creates.
Many investors focus heavily on the preferred return.
For example:
“The deal has a stated preferred return.”
But a preferred return is not the same thing as a guaranteed return.
Investors need to understand the full distribution waterfall.
Questions include:
The waterfall tells the full story behind the headline number.
Whether investing through a syndication or a private real estate fund, liquidity deserves serious consideration.
These are generally not public stocks.
There may be no active secondary market where an investor can simply click “sell.”
The SEC specifically warns that securities purchased through private placements can be highly illiquid and that investors may have difficulty finding buyers for those securities.1
A syndication may project a five-year hold.
That does not necessarily mean investors will receive their money back exactly five years later.
The property might sell sooner.
Or it might make financial sense to hold longer.
Market conditions, financing conditions, property performance, and buyer demand can all affect the exit.
Funds vary even more.
A closed-end fund might operate for many years before fully liquidating its portfolio.
An evergreen fund may offer periodic redemption opportunities, although those redemptions can be subject to limits, gates, available liquidity, and other conditions.
Along with the projected hold period, ask:
“What happens if I need my capital before the hold period ends?”
If the answer is unclear, investors should assume the capital is illiquid.
This is another important distinction.
With a single-asset syndication, investors often fund their investment in connection with the property's acquisition.
Your $100,000 may therefore become invested relatively quickly.
A fund can work differently.
An investor might commit $500,000, but the manager may draw that capital gradually as acquisitions are identified.
This can create a capital-planning consideration.
If only $100,000 of your $500,000 commitment has been called, the remaining $400,000 may technically remain yours.
But it cannot necessarily be treated like completely unrestricted capital.
The fund may issue another capital call.
Investors therefore need to understand:
Committed capital and invested capital are not always the same thing.
This may be the biggest practical takeaway.
The due diligence process should change depending on what you are buying.
You are evaluating two things:
The asset and the operator.
Property-level questions may include:
Then evaluate the sponsor.
The underlying manager matters even more.
You may want to examine:
Sophisticated investors also ask managers about the deals that went wrong.
You often learn more about an operator from how they handled a difficult investment than from the investment that performed exactly according to plan.
Consider an investor evaluating a $20 million multifamily property.
The sponsor plans to raise $7 million from investors and finance the remainder through debt.
Before committing capital, investors may be able to evaluate the exact:
If the investor likes the sponsor but does not like the property, they can decline the opportunity and potentially evaluate the sponsor's next transaction.
That selectivity is one of the defining characteristics of deal-by-deal syndication investing.
Now imagine the same sponsor raises a $75 million fund.
The fund's mandate is to acquire value-add multifamily properties throughout several growing Southeastern markets over the next three years.
An investor may commit $500,000.
At the time of investment, perhaps only two properties have been identified.
The remaining acquisitions will be selected by the manager later.
Here, the investment thesis changes.
In a syndication, the investor is effectively saying:
“I believe in this property.”
In this fund, the investor is saying:
“I believe in this team's ability to repeatedly make intelligent investment decisions.”
That requires a different level of trust.
Neither structure is inherently superior.
They solve different problems.
A syndication can make sense for investors who value the ability to evaluate investments deal by deal.
A fund can make sense for investors seeking exposure to a broader strategy and who are comfortable delegating more investment selection to a manager.
The more useful comparison is this:
You generally know exactly where the capital is going.
Your capital may ultimately participate across multiple investments.
One asset can significantly determine the outcome.
You are relying on the manager to make future decisions you cannot fully evaluate today.
Both structures carry risk.
The structure you choose determines where the risk sits.
Whether evaluating a real estate syndication or a fund, four areas deserve particular attention.
How much of the sponsor's own capital is invested?
How is the sponsor compensated?
Does the manager's financial outcome meaningfully depend on investor performance?
Projected returns are outputs.
Focus on the assumptions producing them.
A sophisticated investor should want to know what happens when:
Good investor communication matters most when things are not going according to plan.
Understand:
Past performance never guarantees future results.
But experience can reveal how the operator behaves.
Look beyond aggregate returns.
Ask:
There is a major difference between having participated in twenty investments and having successfully navigated twenty investments from acquisition through exit.
Structure, fees, diversification, and liquidity all matter.
But private real estate ultimately involves putting capital into the hands of people who will be responsible for making decisions with it.
That should never be treated casually.
Whether the investment is called a real estate syndication, private fund, joint venture, or another structure, the underlying questions remain surprisingly consistent:
Who is making the decisions?
How do they make those decisions?
How are they incentivized?
What happens when their assumptions are wrong?
And are they disciplined enough to protect investor capital when conditions change?
The strongest investment opportunities are the ones where the projections, structure, strategy, underwriting, incentives, and people responsible for execution make sense together.
That is where real due diligence begins.
Real estate syndication is a structure in which multiple investors pool capital to participate in a real estate investment, typically with a sponsor or General Partner responsible for finding, acquiring, financing, and managing the property while Limited Partners participate passively.
A real estate syndication generally raises capital for a specific identified property or project. A real estate fund typically pools investor capital according to a broader investment strategy and may invest across multiple properties.
Generally, no. Investments made through private real estate syndications are typically illiquid. Investors should carefully review transfer restrictions, expected hold periods, and potential exit provisions before investing.
The sponsor or General Partner generally controls day-to-day investment and property decisions. Limited Partners are typically passive, although operating agreements may provide investors with voting rights over certain major decisions.
Depending on the investment, sponsors may charge acquisition, asset-management, financing, construction-management, property-management, refinancing, or disposition fees in addition to participating in profits through a promote or carried-interest structure. Fee structures vary significantly by transaction.
A fund may provide greater diversification because it can hold several investments instead of one property. Investors should still examine geographic, asset-class, financing, tenant, and strategy concentration because owning multiple properties does not necessarily eliminate correlated risks.
Many private real estate syndications are offered under Regulation D. Rule 506(c) offerings may only sell to verified accredited investors, while Rule 506(b) can permit participation by a limited number of qualifying non-accredited investors, subject to additional requirements. Investors should review the specific securities exemption used by each offering.
This article is for educational purposes only. Novacrest offerings are available to verified accredited investors through official offering documents. Nothing in this article should be considered investment, legal, tax, or financial advice. Private real estate investments involve risk, including possible loss of principal, and investors should review applicable offering documents and consult appropriate professional advisers before investing.
For generations, investing has been synonymous with the stock market. Opening a retirement account, buying a collection of stocks and bonds, and staying invested, serves as the traditional strategy that has helped millions build wealth.
Today, a growing number of investors are exploring alternative investments like private real estate, private credit, infrastructure, aviation, and private equity, which are no longer reserved for large institutions or ultra-high-net-worth individuals. These opportunities are becoming an increasingly important component of diversified portfolios and provide exposure to parts of the economy that public markets don’t reach.
Companies listed on the New York Stock Exchange or Nasdaq represent only a fraction of America’s businesses. Research from KKR notes that approximately 85% of U.S. companies generating more than $100 million in annual revenue remain privately owned, meaning many of the country’s fastest-growing businesses never become available through a traditional brokerage account.
Since 2012, private equity-backed companies have also outnumbered publicly traded companies in the U.S. Investors relying exclusively on public markets are participating in only part of the economy, and alternative investments create access to opportunities that exist outside of those exchanges.
For years, some of the world’s most sophisticated investors (including pension funds, insurance companies, family offices, and university endowments) have allocated meaningful portions of their portfolios to alternative assets.
Because investors aim to build portfolios that can perform across different economic environments, they participate in alternative assets, which can offer:
According to KKR’s 2025 survey of registered investment advisors, nearly half of advisors already allocate at least 10% of client assets to private markets, and 81% expect to maintain or increase those allocations over the next five years. This trend reflects a broader shift in how professional investors think about diversification.
Many investors believe they’re diversified because they own multiple companies, but during periods of market stress, those companies often perform similarly. True diversification comes from owning assets driven by different economic forces like:
Each of these alternative opportunities responds differently to changes in interest rates, inflation, consumer spending, or market volatility. Although this doesn’t eliminate risk, it ensures that your portfolio isn’t dependent on a single source of returns.
Since public markets react instantly to headlines, a change in interest-rate expectations, geopolitical tensions, or quarterly earnings can dramatically shift prices within hours.
Private investments’ value is driven by operational performance, contractual income, underlying asset appreciation, and long-term business fundamentals, which is why institutional investors often view alternatives as a stabilizing component of broader portfolios.
As KKR’s Global Asset Allocation team notes, private credit, infrastructure, and real estate can provide more durable cash flows, while improving portfolio resilience during periods of heightened market volatility.
Cambridge Associates’ benchmark research shows U.S. private equity has demonstrated more consistent outperformance over public markets across investment periods of 10 years and longer, although shorter periods have produced mixed results.
Since different assets each serve their purpose, building a portfolio capable of producing consistent long-term outcomes, reduces concentration risk. A resilient portfolio often includes growth, income, capital preservation, and inflation protection.
Alternative investments typically involve longer investment horizons, reduced liquidity (compared to publicly traded securities), higher investment minimums, and a greater importance of manager selection.
These characteristics are considerations that investors should understand before allocating capital. Illiquidity, in particular, can be both a risk and a potential advantage. Investors willing to commit capital over longer periods may gain access to opportunities unavailable in public markets, if that investment horizon aligns with their financial goals.
Markets like private businesses, real estate, infrastructure, private lending, and specialty assets collectively represent trillions of dollars in investment opportunities and continue attracting increasing allocations from institutions seeking greater diversification and multiple sources of return.
To discuss how you can build a portfolio that isn’t dependent on the market, book a call with our Investor Relations Team here to help expand the definition of what investing can look like.
According to Realtor.com’s 2026 Housing Supply Gap Report, the United States is approximately 4.03 million homes short, with the shortage widening for the third consecutive year. Freddie Mac’s ongoing housing research also concludes that America remains structurally undersupplied by millions of homes, and that closing this gap will require years of sustained construction.
As builders increase production, they navigate higher material costs, labor shortages, land constraints, financing challenges, and regulatory hurdles that continue to slow new housing development. The National Association of Home Builders has identified these barriers as key reasons housing supply continues to lag demand.
Since each market has its own unique housing needs, long-term success comes from delivering the types of residential homes buyers are actively seeking.
Novacrest continues identifying underserved opportunities within residential housing and developing projects that align with local demand. Rather than forcing every opportunity into a single product type, the Residential Income Fund focuses on building residential projects that make sense for the communities we’re serving and the long-term fundamentals supporting those markets.
The housing market is made up of thousands of local markets, each driven by its own economic fundamentals. We focus on regions where the data supports population growth, employment expansion, and housing demand that consistently outpaces new supply.
Our criteria identifies markets with sustained inbound migration, driven by employment or lifestyle; job creation across multiple industries, rather than a single employer; a documented gap between housing demand and available inventory; and long-term growth characteristics that outlast short-term market cycles.
Every acquisition is evaluated through disciplined underwriting, and focuses on purchasing opportunities at or below 70% of estimated completed value. Each market is selected only when long-term demographic trends support the investment.
Because we build high-demand homes, in carefully-selected markets, with the discipline that long-term investing requires, we’ve created resilience when markets inevitably shift.
Novacrest co-founders, Kiani and Anwar Kharfan created the Residential Income Fund for investors who want their capital working in real residential assets, and they remain directly involved in every part of the business, from investor communication and operations to acquisitions, development, and asset management.
If you’d like to understand more on the Residential Income Fund and how we evaluate opportunities, you may schedule a conversation with our Investor Concierge today.
For months, the market has awaited rate cuts, which have not yet arrived, and increasingly, seem not to be coming anytime soon.
The Federal Reserve is holding rates in the 3.5% to 3.75% range, and expectations for cuts continue to get pushed back. Some institutions are now projecting few or no cuts in 2026.
Simultaneously, inflation remains above the Fed’s 2% target, and treasury yield expectations are creeping higher. External pressures, like energy prices and geopolitical instability, continue to add uncertainty.
On the surface, the market appears stable. Savings accounts and CDs are yielding ~4 to 5%, the economy is still expanding and public markets remain active.
But underneath, investor behavior is shifting.
With inflation still elevated, 4 to 5% yields are barely keeping pace, in turn, limiting real wealth creation.
Equities continue reacting to inflation data, rate expectations and global instability, resulting in inconsistent performance and lower conviction.
Today’s environment presents a clear tradeoff, where safer investments yield low returns, and higher returns seem only possible with volatile or uncertain opportunities.
That gap leaves many investors with no clear allocation strategy.
Due to lack of compelling alternatives, high-income investors are holding significant capital in cash positions, brokerage accounts and retirement vehicles.
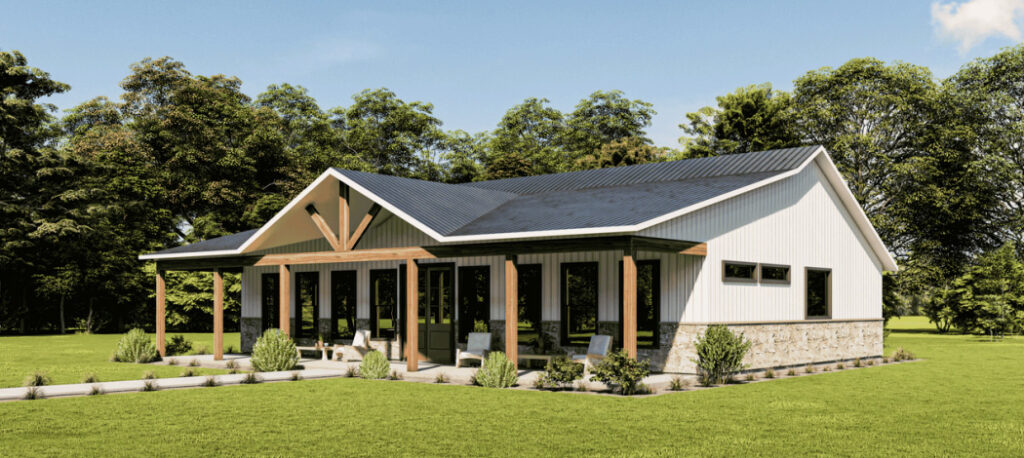
While interest rates dominate headlines, the core driver of real estate value remains supply.
Supply remains structurally constrained, as the U.S. Is underbuilt by millions of homes:
Despite variation in methodology, the conclusion is that the U.S. does not have enough housing.
Recent data (sources listed below) shows that existing home sales have declined, yet inventory remains tight.
Although buyer demand has slowed, supply has not meaningfully improved. The market is slowing due to constrained supply conditions, rather than oversupply.
Housing markets are ultimately governed by a simple dynamic:
When supply is constrained and population demand continues, prices and demand resilience follow.
This results in rising home prices, cautiously optimistic builders and long-term housing fundamentals remaining intact.
This combination of a supply-constrained environment with elevated financing costs, makes for a non-traditional real estate cycle.
This type of environment filters weak operators and rewards disciplined, execution-focused strategies.
In this market, success is driven by entry price discipline, cost control, buyer targeting and execution speed.
Novacrest is positioned within a specific gap created by this environment.
Between low-yield traditional fixed income and higher-risk, market-dependent investments, our approach focuses on:
Novacrest not only diversifies an investor’s portfolio, but also allocates to income-producing strategies that function in today’s conditions.
For years, markets rewarded growth, multiple expansion and long-term upside.
Now that our environment has shifted, today’s markets reward:
The Fed holding rates is accelerating a broader shift in investor behavior, forcing a decision between remaining in low-yield, low-conviction positions and moving into strategies designed to produce income now.
As established earlier, higher rates, slower transaction volume and inflation don’t stop real estate, but remove weak operators.
Novacrest’s strategy is built to operate in today’s environment and does not depend on a favorable one.
Our buyers (cash buyers, move-up buyers, out-of-state buyers, and working professionals) are less dependent on financing, which helps stabilize demand even as rates remain elevated.
We focus on areas with population growth and sustained housing demand, ensuring a consistent buyer pool.
We underwrite with conservative pricing, built-in margins and flexibility for incentives, which allows us to maintain velocity, rather than await market appreciation.
As the builder, we control costs, timelines, pricing and exit strategy.
Execution in the Diversified Real Estate Fund is internally underwritten and managed.
We do not assume falling interest rates, rapid appreciation, or ideal market conditions.
Each deal is structured to perform in today’s environment.
The market today is defined by two realities: rates remain higher long-term, and housing supply is structurally constrained.
This combination reshapes how capital is deployed and creates a clear separation between passive investing and execution-driven strategies.
Novacrest is built for today’s environment as a solution for investors seeking consistent, income-producing opportunities, backed by real assets.
Book a call with us today and bring your questions to our concierge team.
The Wall Street Journal: https://www.wsj.com/buyside/personal-finance/banking/high-yield-savings-rates-today-4-9-2026
The Wall Street Journal: https://www.wsj.com/buyside/personal-finance/banking/cd-rates-today-4-9-2026
Realtor: https://www.realtor.com/research/us-housing-supply-gap-2026/
National Association of Home Builders: https://www.nahb.org/news-and-economics/press-releases/2026/02/2026-housing-outlook-ongoing-challenges-cautious-optimism-and-incremental-gains
Eye On Housing: https://eyeonhousing.org/2026/02/the-size-of-the-housing-shortage-2024-data/
Window & Door: https://www.windowanddoor.com/article/2026-housing-market-outlook
National Low Income Housing Coalition: https://nlihc.org/news/nlihc-releases-gap-2026-shortage-affordable-homes
AP News: https://apnews.com/article/53aee15e8a48b930f286b19475b861ac
Washington Post: https://www.washingtonpost.com/business/2026/02/04/us-housing-shortage-millions/